
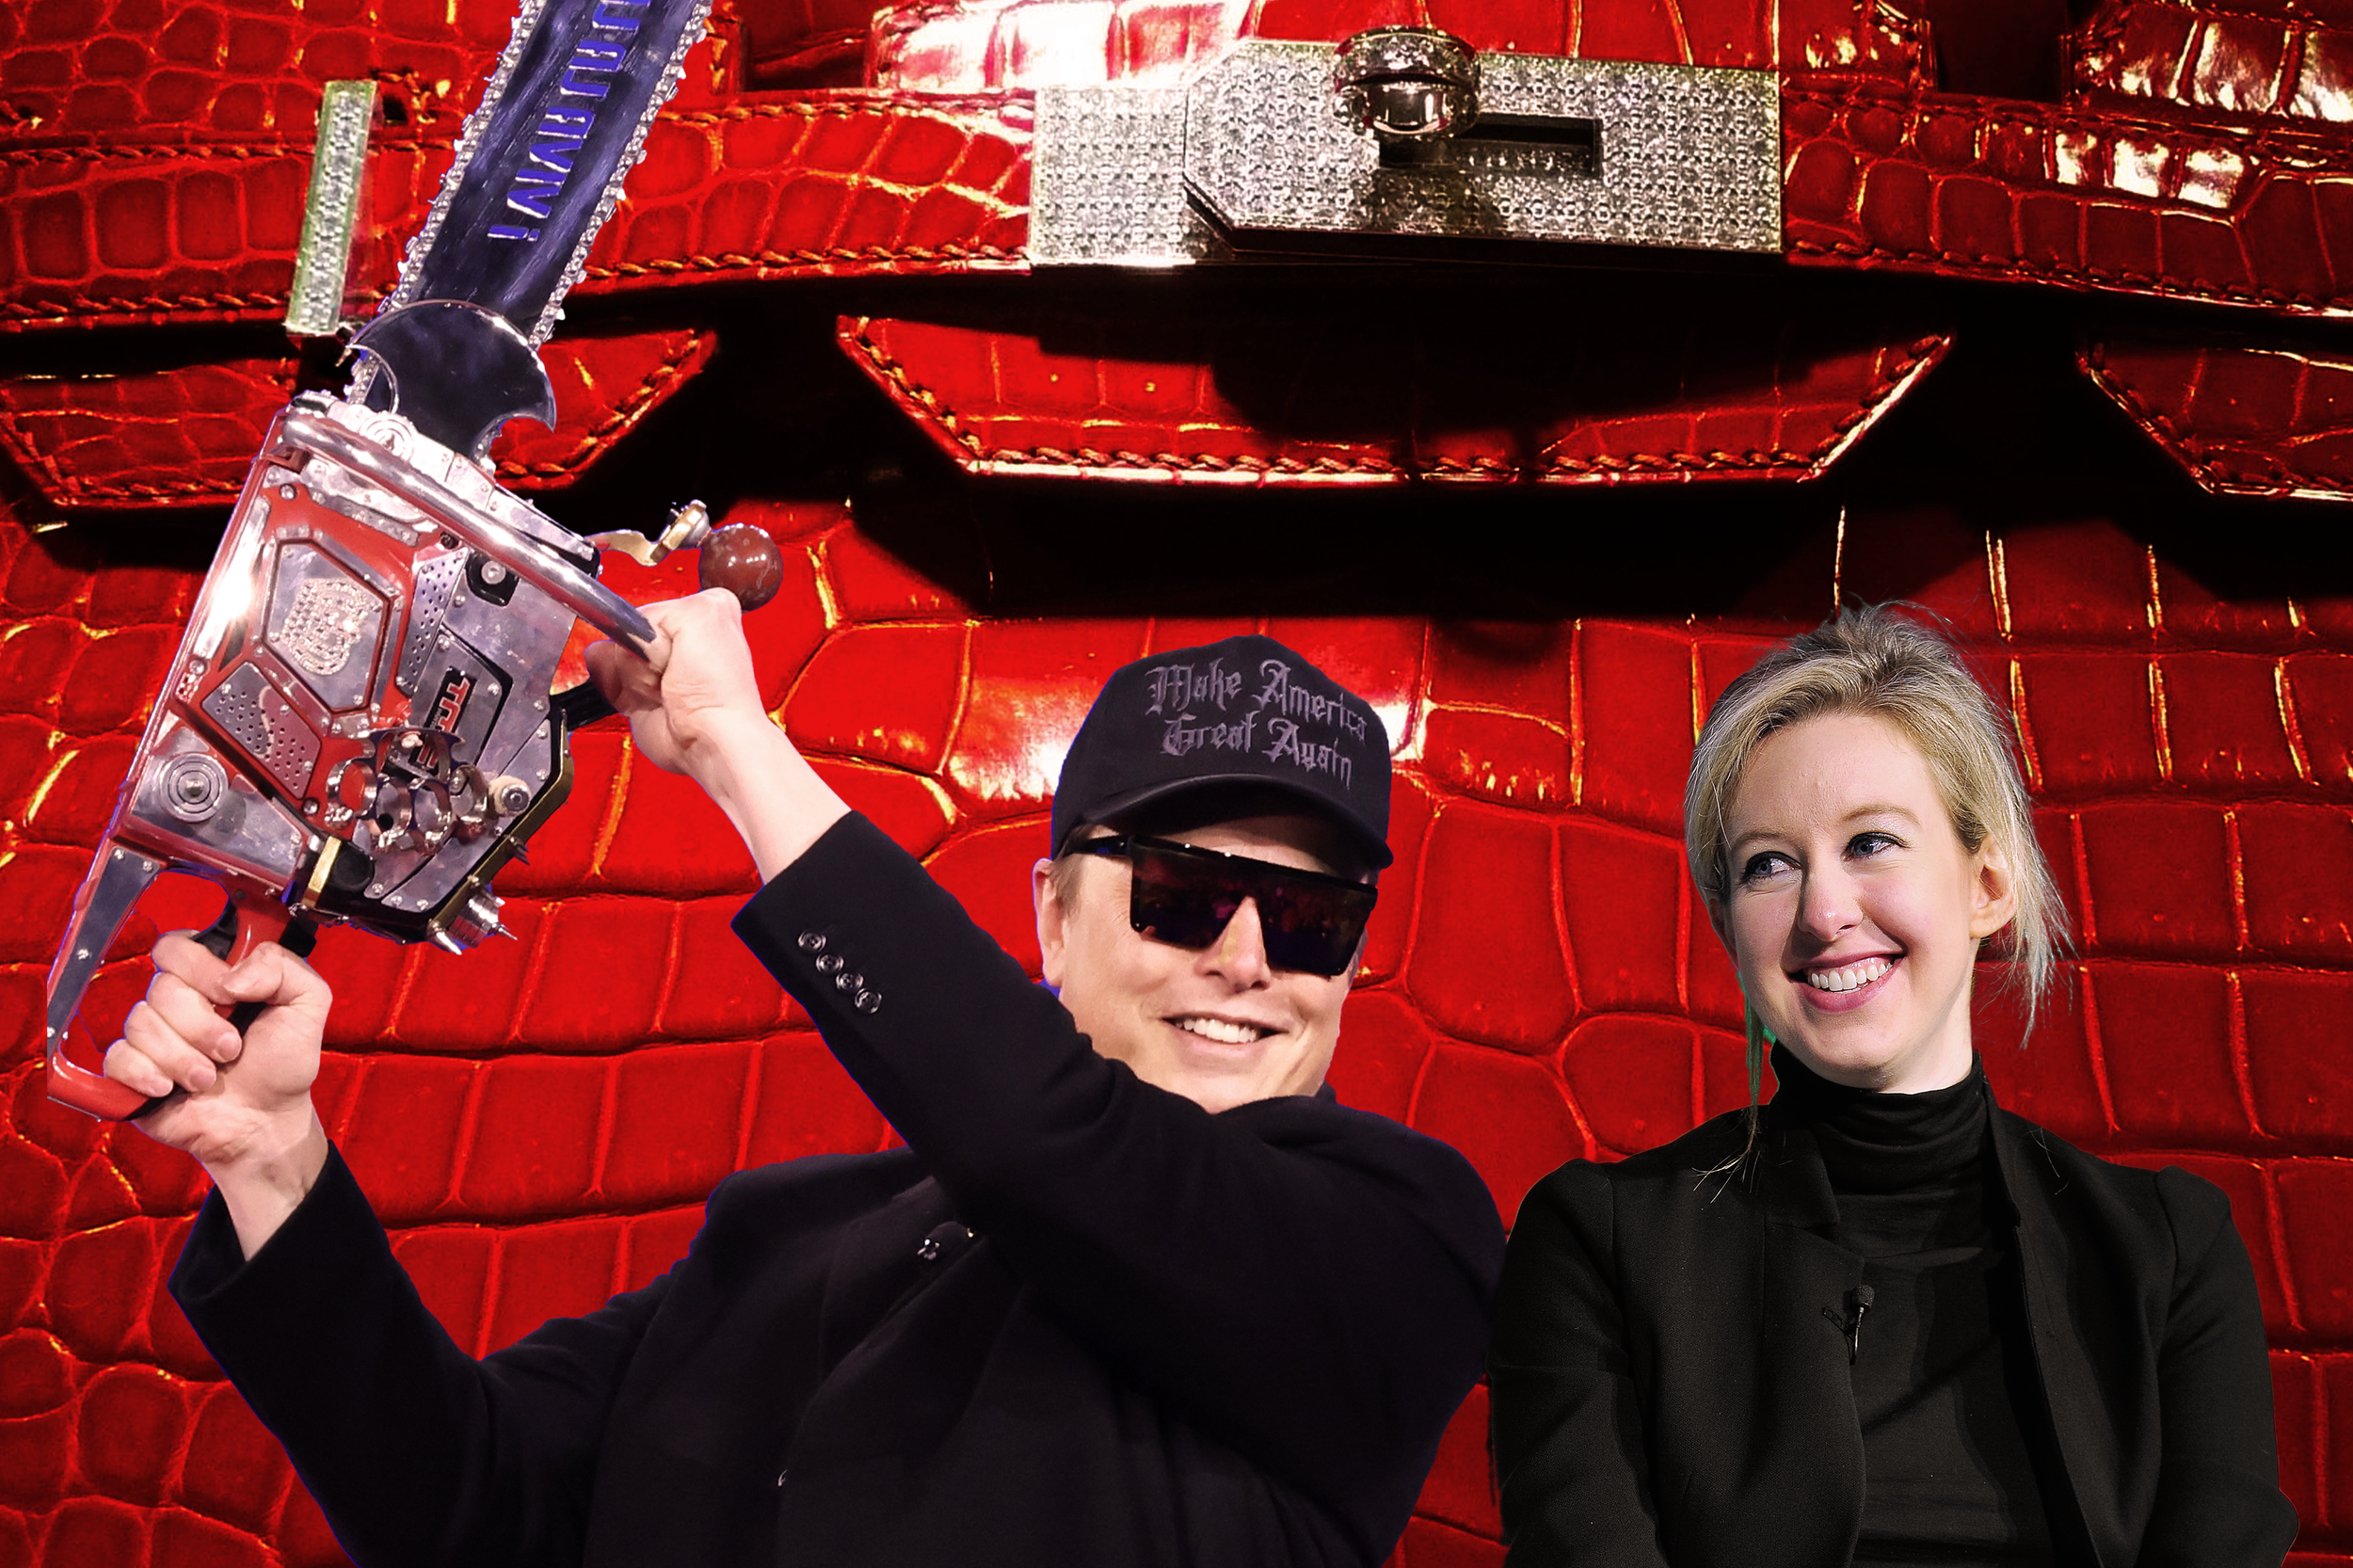
Elon Musk, Elizabeth Holmes and the fabrication of value in the financial market
“The purpose of this was not to litigate the science […] It starts with who I am and what my intent was, and still is.“ (Elizabeth Holmes at the beginnning of the documentary You Can See Everything. 2026.)
“Economics is not an evolutionary science—by the confession of its spokesmen.” (From Thorstein Veblen’s 1898 essay Why is Economics not an Evolutionary Science?)
Elon Musk and Elizabeth Holmes have a crucial point in common.
One built a business empire around electric cars, rockets, and satellites. The other promised to revolutionize medicine with a technology capable of performing various laboratory tests in a machine the size of a printer. One continues to be treated as one of the most influential businessmen in the world, and the other was convicted of fraud against investors. But both understood that the value of a company does not depend exclusively on what it produces, but rather on what it manages to make others believe it will produce.
The financial market trades products and results as much as it trades expectations. And, when expectation becomes more important than reality, an extraordinary space opens up for the creation of value.
For years, Holmes, founder of Theranos, sold the idea of a supposedly revolutionary technology capable of performing fast, cheap blood tests with small samples. The company was valued at billions, while its CEO became a symbol of a new generation of Silicon Valley entrepreneurship.
The problem was that the technology didn’t work, and secrecy was the most effective tool to hide this. Trade secrets are a convenient justification for corporate opacity. Under the guise of protecting intellectual property, companies can restrict access to information that could otherwise expose the discrepancy between their public promises and operational reality.
The distinction between protecting innovation and concealing failure becomes increasingly difficult to discern when the same corporations control both the technology and the information available to verify their claims.
Musk operates on a different scale, but also within the logic of transforming public statements into economic events.
In August 2018, Musk announced that he was considering taking Tesla private at $420 per share and stated that funding was secured. The statement triggered a surge in the company's stock that day. The problem, according to the SEC, was that there was no secured funding, nor concrete agreements with potential financiers. The operation was still subject to several uncertainties that were not adequately communicated to the public.
The SEC filed fraud charges against Musk and Tesla. Both accepted a civil settlement, without admitting or denying the allegations, paying $20 million each. Musk also stepped down as chairman of Tesla’s board, and the company had to establish controls over its public communications.
In 2025, the SEC filed another lawsuit against Musk, alleging that he delayed disclosing his more than 5% stake in Twitter, saving at least $150 million at the expense of other shareholders. In 2026, the lawsuit was referred for closure through a settlement involving a $1.5 million fine paid by Musk's trust, without admission or denial of the allegations.
In other words, Musk has already suffered regulatory sanctions and faced lawsuits. Why do these sanctions seem so small in the face of his ability to continue influencing the market?
The power of controlling the narrative
It is difficult to hold executives accountable whose persona has become a central part of their companies’ value. The application of fines, especially when it does not substantially alter an entrepreneur’s economic position, may represent a manageable cost, not an effective deterrent.
Theranos never had publicly traded shares. Holmes manipulated private investors by building a public narrative of scientific innovation that helped legitimize the company and attract capital. Musk, in turn, operates directly in the public market, where statements transmitted to millions of people can immediately alter the perceived value of a company and influence investment decisions. When business leaders use their persona to interfere in price formation, the impact goes beyond their own shareholders and affects the market’s ilusion of integrity.
The same concentration of personal influence becomes even more consequential when it extends to the production and circulation of information. When asked to explain why creating a collective consciousness matters, Musk struggles to articulate a clear purpose beyond the technological ambition itself. His inability to explain the ultimate goal raises questions about whether his vision is genuinely about collective intelligence or about consolidating control over the infrastructure through which information circulates and narratives are shaped.
Thorstein Veblen had already observed this phenomenon in the 19th century in Why Economics Is Not an Evolutionary Science?. He questions the claim to construct a universal economic science from static concepts, as if human behaviors and institutions were natural givens, and not products of historical processes. Economics has always needed to be understood as stemming from subjective trends that reflect the decadent values of society. And this only becomes more evident as the centuries go by.
This perspective allows us to observe that the market is not a neutral mechanism for discovering value. It is also a social institution, built by power relations and conventions. Price is not necessarily an objective measure of the utility or productive capacity of something. It is the result of social and economic relations that determine what will be recognized as valuable.
Hermès’ Birkin bags offer a particularly interesting example of this construction. A Birkin bag doesn’t cost tens or hundreds of thousands of dollars simply because its leather, its manufacture, or its functionality justify that price. Its value depends on a strategy of exclusivity and social prestige. Difficulty of access is a crucial part of the product. The consumer doesn’t just buy a bag; they buy the social recognition associated with the possibility of owning it. And scarcity, real or managed, directly participates in price formation.
While in the luxury market the symbolic construction of value is an explicit part of the business, in the financial market there is an expectation that a company’s valuation will have some verifiable relationship with its ability to produce results. The problem begins when the narrative replaces this verification and impacts the perception of value.
There is something especially Veblenian in asking whether the problem lies with the entrepreneurs who exploit the rules or with the economic institutions that transform the exploitation of these rules into a sign of success. Birkin, Theranos, and Musk’s companies represent different facets of how capitalism not only assigns value to things, but also sees the manipulation of that value as part of humanity’s evolution.
Holmes sold the image of a scientific revolution before possessing the technology to support it. Musk transformed his image as a visionary inventor into a central component of the perceived value of his companies. In both cases, the founder’s personality begins to function as a kind of intangible asset, capable of attracting investments and sustaining expectations that do not always correspond to concrete results. Just like the Birkin buyer’s persona can become as economically valuable as the object itself.
The difficulty in distinguishing economic success from narrative success is historical. When a company is valued more because its founder is celebrated as a genius than for what it actually produces, the problem becomes structural.
Holmes and Musk represent two manifestations of this contradiction. One was condemned for transforming a technological promise into an instrument of fraud. The other continues to exert enormous economic influence despite repeated conflicts with regulatory bodies. Both reveal a system in which the ability to convince can precede, and even surpass, the ability to produce.
Perhaps the financial market is not simply losing touch with reality. Perhaps we are facing a capitalism in which the very fabrication of an investable reality becomes an increasingly lucrative business.
Mirna Wabi-Sabi

Mirna is a Brazilian writer, editor at Sul Books and founder of Plataforma9. She is the author of the book Anarcho-transcreation and producer of several other titles under the P9 press.